
Your Insurance Company Just Lost Two of Its Favorite Moves
Insurability is now the single most common reason I watch an LA deal die. Not price. Not financing. A buyer gets to day eighteen, cannot get a quote that works, and walks.
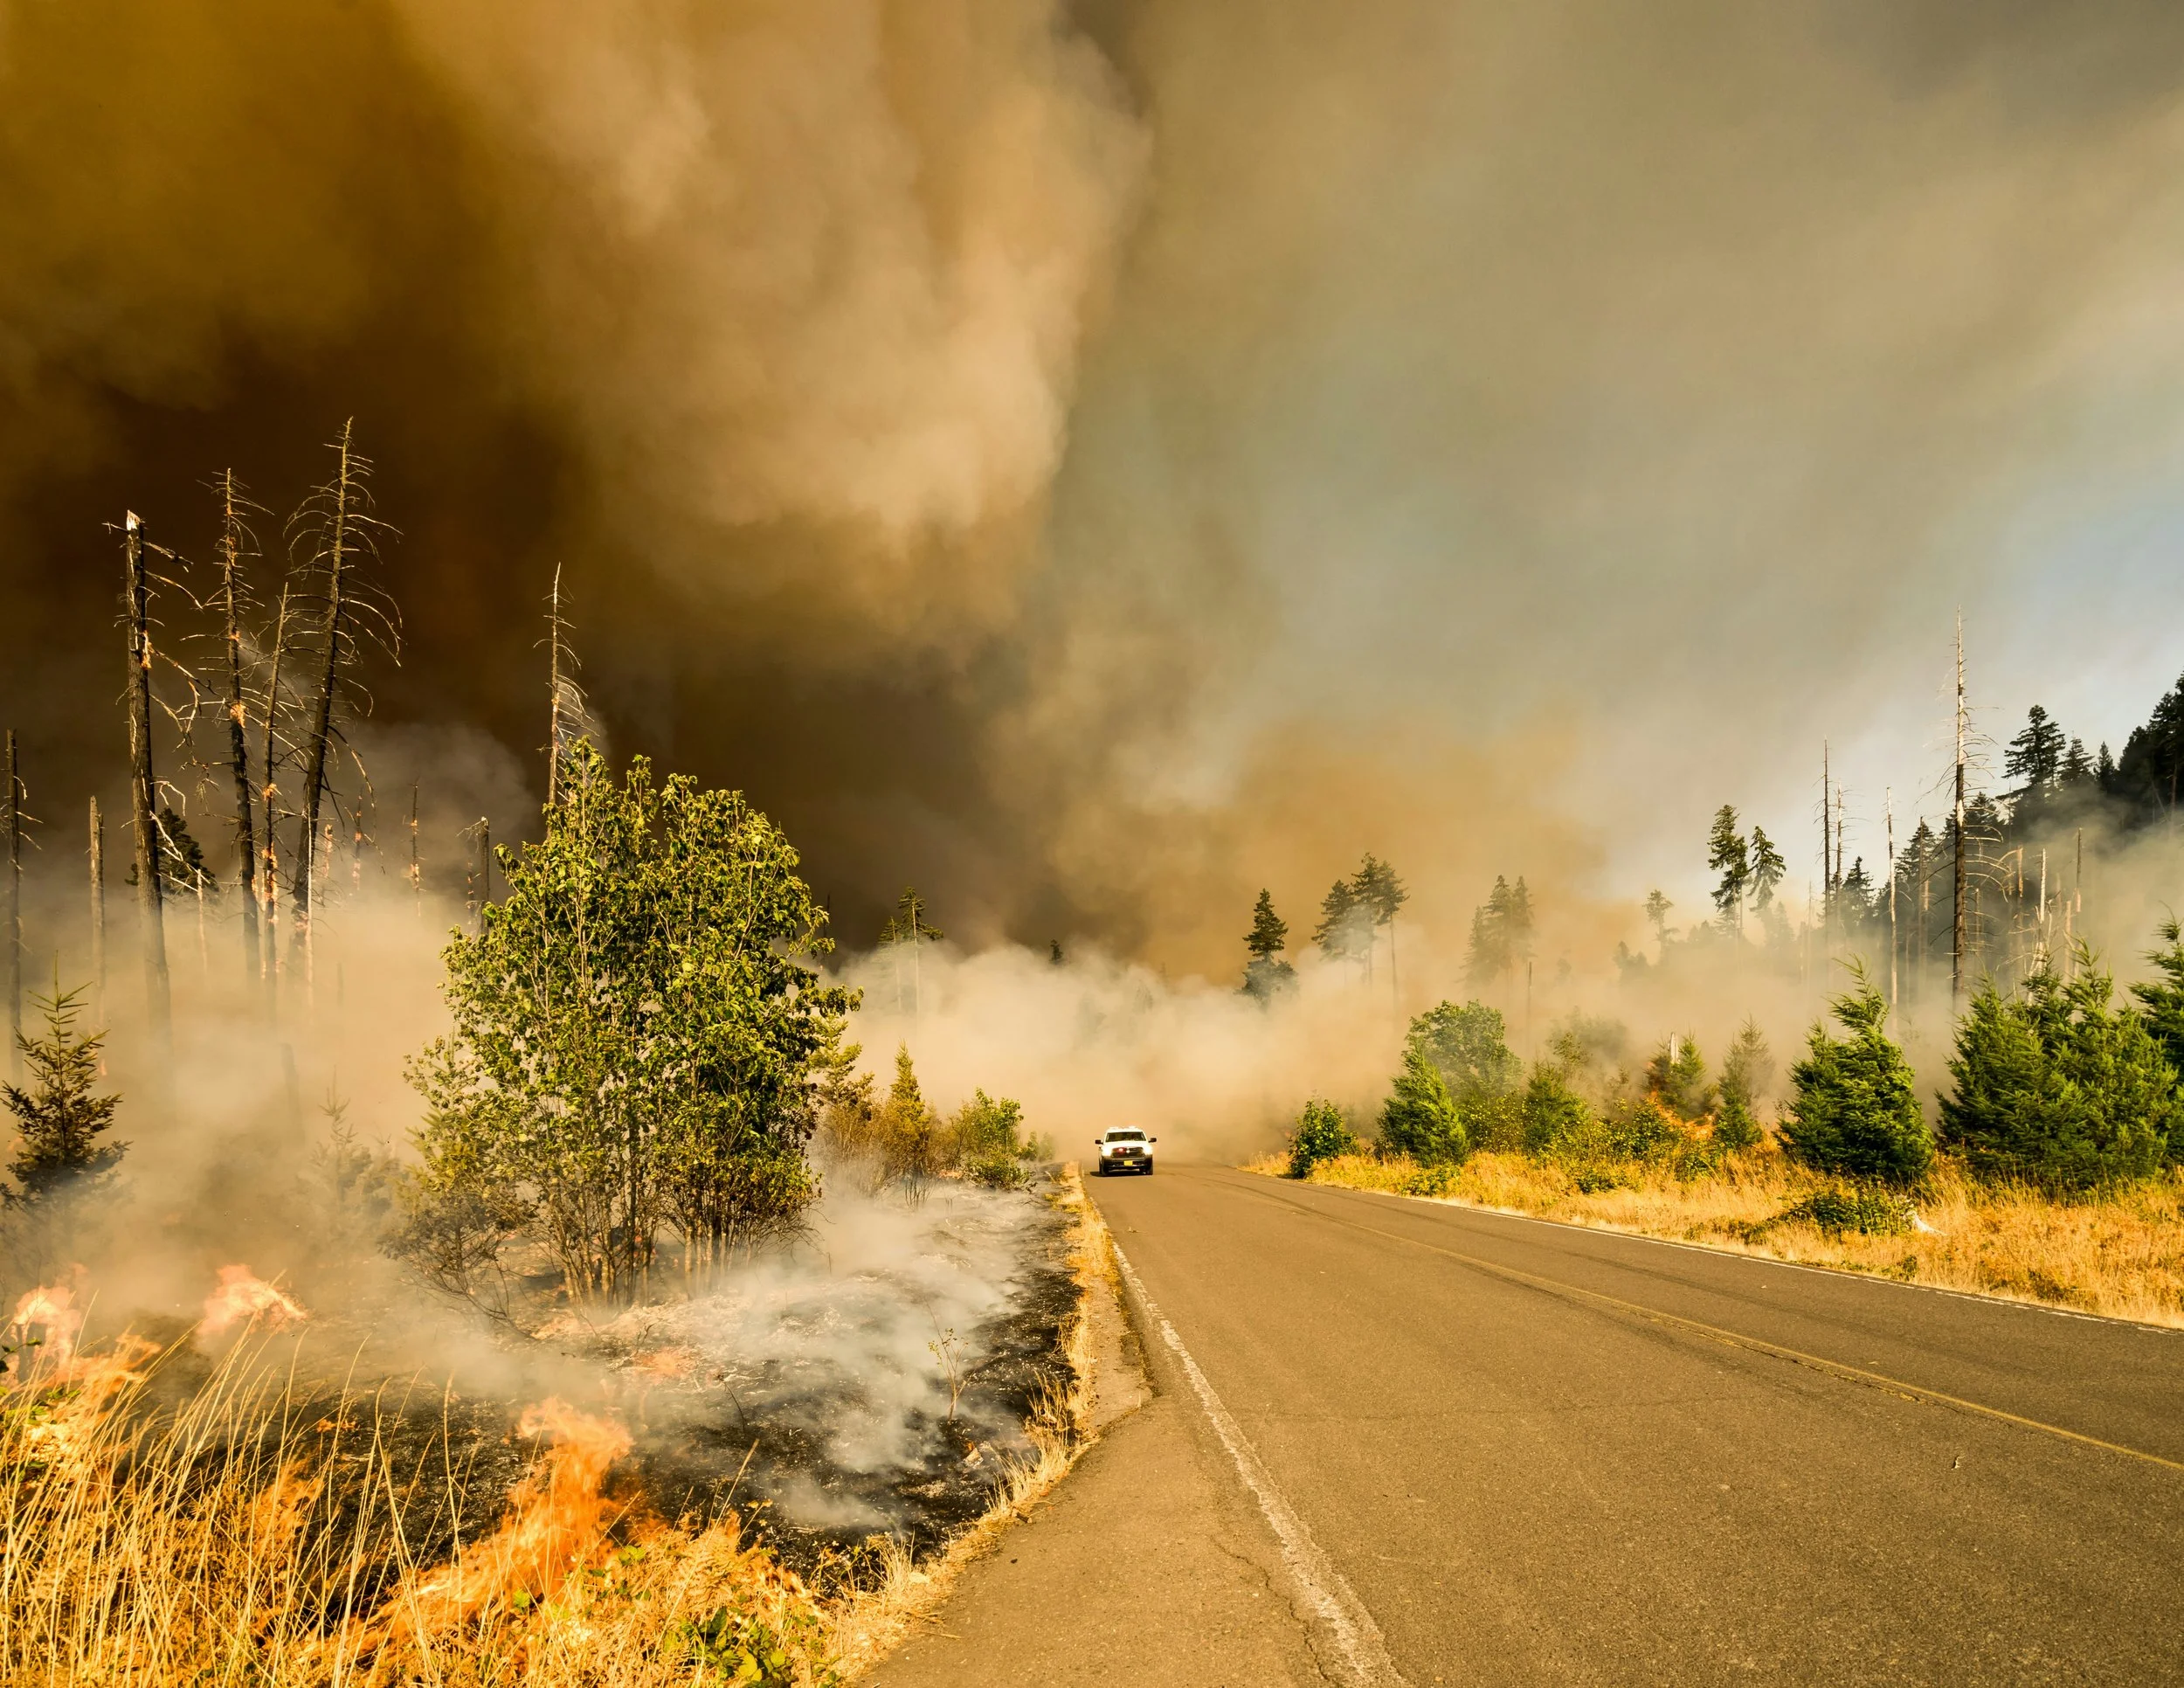
So when California's bill-signing deadline passed this week and three insurance bills made it through, that mattered more to my clients than most of the seventy-odd housing bills that got all the headlines. Here is what actually changed — and, just as importantly, what got vetoed.
1. The post-fire protection window doubled
AB 2038, authored by Assemblymember John Harabedian of Pasadena with Assemblymember Rick Zbur of Hollywood as co-author, extends the existing ban on cancellation and non-renewal for properties in or near a fire perimeter after a declared state of emergency. That protection used to run one year. It now runs two.
And if your primary residence is a total loss, the mandatory renewal period goes from 24 months to at least 36 months, covering at least three consecutive annual renewals.
If you have watched anyone try to rebuild after a total loss, you know exactly why that second number matters. Rebuilds in Los Angeles do not finish in 24 months. Permits alone can eat a year. Families were hitting the end of their protected window with a half-built house and no carrier willing to write the policy.
2. Non-renewal stopped being a form letter
SB 1301, from Senator Ben Allen, is the one I think will change day-to-day behavior the most. Starting next year, a carrier that wants to non-renew you has to:
• Give at least six months' advance notice
• State the specific reasons for the decision
• Give you an opportunity to make repairs or mitigations and keep the coverage
And it bars non-renewal for three things that frankly should never have been permitted in the first place: because you called to ask about filing a claim, because you filed a claim that was not paid or not payable, or because you filed a claim that fell inside your deductible.
I have had owners tell me they were afraid to phone their own insurance company. That fear was rational. It is now also, as of January, against the law to act on.
A third bill, SB 876, also dealt with fire and residential property insurance and was signed the same day. I have not read its provisions closely enough to characterize them, so I am telling you it exists rather than telling you what it says.
3. The part nobody is posting about
Two insurance bills were vetoed on September 27. One of them was SB 877, which would have required transparency around how carriers build their loss estimates. The other was SB 878, on insurance business practices.
That veto is the whole story, and if you only post the good news you are going to look naive in about six months.
What the Legislature delivered this year is process. More notice. More time. More explanation of the decision to drop you. What it did not deliver is any requirement that a carrier show its math on what your home is worth or what your loss is worth. The pricing power and the valuation discretion are untouched.
So the honest summary is: it is harder to get dropped, and just as hard to argue about your number.
The multifamily angle — and this is the important one
I sell apartment buildings, and this is where I have to slow you down, because I think a lot of owners are about to assume something that is not true.
Every bill above is written as residential property insurance. If you own a fourplex you occupy, or a single-family rental, you are very likely inside that definition. If you own a 40-unit building in Van Nuys, your property is almost certainly written on a commercial policy — and a commercial policy is a different animal under a different part of the Insurance Code.
So do not read the headline and assume the six-month notice requirement or the two-year post-fire protection attaches to your apartment building. I would not tell a client that without confirming it, and I am not going to tell you that here. What I would do is call your insurance broker with one specific question: is this property written as residential or commercial, and do this year's protections reach it? That is a five-minute call with a real answer.
I raise it because the gap itself is the story. The hardest insurance conversations I have had in the last two years were not about houses. They were about 1960s stucco apartment buildings in hillside-adjacent submarkets, where the owner got a non-renewal, the replacement quote tripled the expense line, and the deal I was working repriced by seven figures on the debt coverage alone. Those owners got process protections for their house this year and, as far as I can tell, not for their building. If you are underwriting an apartment acquisition in a fire-exposed pocket right now, keep treating insurance as a live risk rather than a solved one.
When this hits
January 1, 2027 for the package. AB 2038's effective date is confirmed; the others follow the standard January 1 rule for bills signed without an urgency clause.
Which means the back half of this year is the window where none of it applies yet. If you are mid-transaction in a fire-exposed pocket right now, you are still operating under the old rules.
What I would do about it
Three things, in order.
First, if you have received a non-renewal notice in the last few months, do not assume it is final and do not assume the new rules help you — they are not retroactive. But do get a second read on whether a mitigation package changes the carrier's answer, because that is now the explicit legal framework going forward and some carriers are already operating that way.
Second, if you are listing a property anywhere near a fire perimeter, get insurability answered before you go to market, not during escrow. I have started treating a current, bindable quote as a listing document in the same category as a termite report. It is the difference between a clean close and a fourth price reduction.
Third, if you are buying, ask the seller directly whether the property has been non-renewed before. That question is going to get more useful, not less, as the notice requirements kick in.
If you want help thinking through what any of this means for a specific property, that is a phone call, not a sales pitch. 310.922.6124.
General information for property owners, not legal or insurance advice. I am a real estate broker — for coverage questions, talk to a licensed insurance professional, and for legal questions, an attorney.
Jake Plewa
Senior Director, RE/MAX Commercial & Investment Realty — TR Multifamily
310.922.6124 | jake@apartmentvaluation.com apartmentvaluation.com
Sources
Governor's Office, legislative update 9/30/2026 (AB 2038 signed)
Governor's Office, legislative update 9/27/2026 (SB 1301 and SB 876 signed; SB 877 and SB 878 vetoed)
Office of Senator Ben Allen, SB 1301 release (notice period, cure opportunity, prohibited grounds)
ColoradoBoulevard.net, 9/30/2026 (AB 2038 effective date and authorship)